Regulation as an Enabler, Not a Barrier
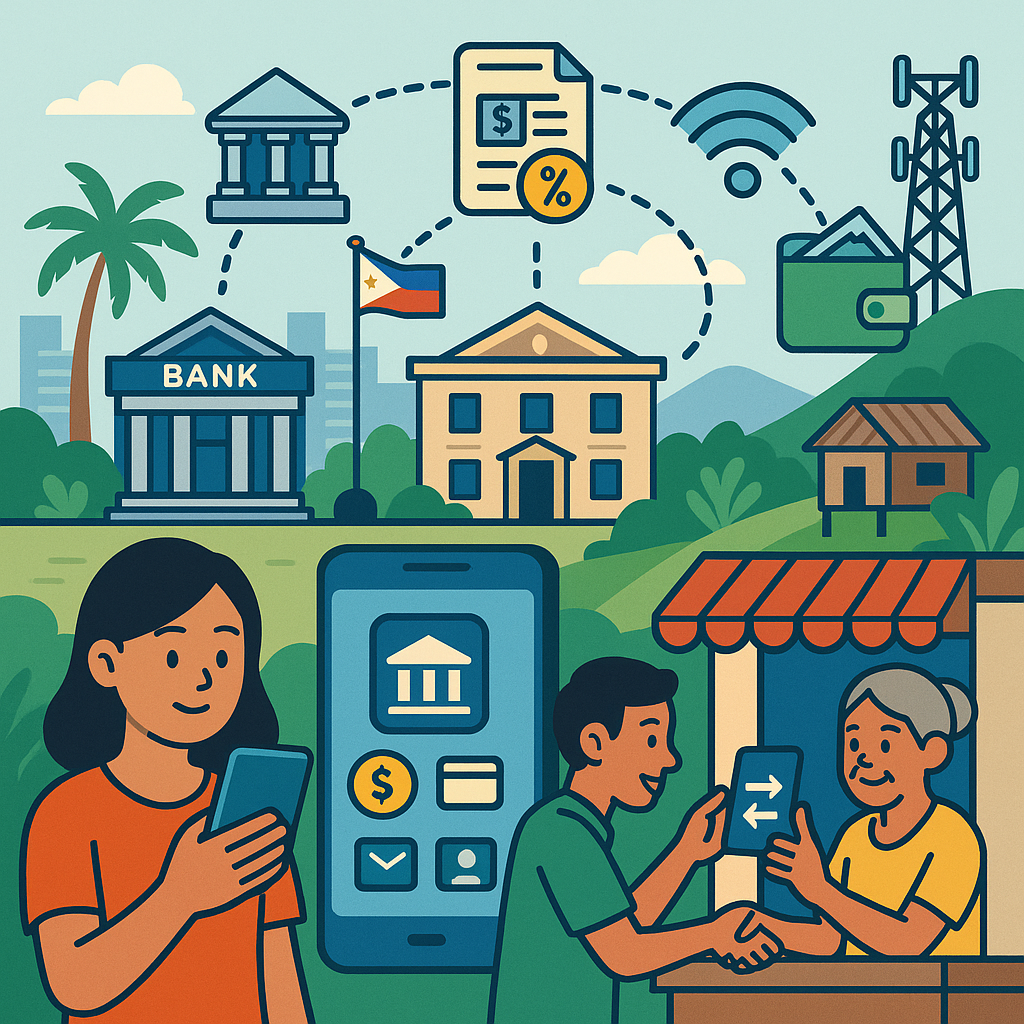
The Philippines’ embedded finance boom has not happened in a regulatory vacuum. The Bangko Sentral ng Pilipinas (BSP) has played a proactive role in shaping the framework that governs how banks and electronic money issuers (EMIs) can embed financial services into non-bank digital platforms. In February 2025, the BSP released draft guidelines for a digital marketplace model, signaling that embedded finance is not only permitted but encouraged.
The draft rules allow institutions to offer both financial and non-financial products and services through a digital marketplace or other online distribution platforms, while prohibiting offerings associated with gambling activities such as online casinos or betting. More importantly, the framework establishes clear expectations around governance, risk management, and consumer protection — the three pillars that determine whether embedded finance builds trust or erodes it.
What the BSP Digital Marketplace Model Allows
Under the proposed guidelines, banks and EMIs operating a digital marketplace can:
- Offer their own core products and services alongside those of third-party providers through a single platform
- Present or display products and services from providers not supervised by the BSP
- Facilitate customer comparison and selection from a range of products and services
- Perform preliminary screening, underwriting, and credit risk assessment
- Act as an intermediary to facilitate payments and transactions, including integrating third-party systems to enable purchases, subscriptions, and order processing
The products that can be offered include retail deposit products, retail and business loan products, plain vanilla debt and equity securities, e-money or payment cards, and retail insurance products. In essence, the BSP is creating a regulatory architecture where a bank or e-money issuer can become a one-stop financial marketplace — within defined risk boundaries.
Capital Requirements and Prudential Standards
The draft guidelines set a high bar for marketplace operators. Interested institutions must have a net worth or combined capital of at least ₱1 billion and meet the BSP’s prudential criteria. These requirements ensure that only financially sound institutions with adequate governance capabilities can operate a digital marketplace, reducing the risk of consumer harm and systemic instability.
The BSP’s rationale is explicit: “The Bangko Sentral recognizes the emergence of new business models and arrangements that will further drive innovation and financial inclusion, as well as promote customer centricity. To remain competitive, it is important for BSP-supervised financial institutions to forge strategic and meaningful ecosystem partnerships with product/service providers which leverage digital distribution platforms or channels”.
Why This Matters for Non-Bank Platforms
For non-bank platforms — from e-commerce marketplaces to ride-hailing apps — the BSP framework creates a clear pathway to embed financial services without becoming a bank. By partnering with a regulated bank or EMI, a non-bank platform can offer savings, credit, or insurance products to its users, while the regulated entity retains responsibility for compliance and risk management.
This model is already being tested. The RCBC–PalawanPay PalaSave partnership, which embedded a savings product into a non-bank app used by 23 million Filipinos, operates within this emerging regulatory framework. Similarly, Netbank’s partnerships with fintech lending apps like JuanHand demonstrate how a rural bank can serve as the regulated infrastructure layer for embedded financial services delivered through non-bank channels.
The Road Ahead: Open Finance and Interoperability
The BSP’s digital marketplace guidelines are part of a broader push toward Open Finance, which would allow consumers to securely share their financial data across institutions with consent. Combined with interoperable payment infrastructure like InstaPay and PESONet, Open Finance could accelerate embedded finance adoption by making it easier for non-bank platforms to access the data needed to underwrite credit and personalize financial products.
The regulatory framework is not yet finalized, but its direction is clear: the BSP is building an enabling environment where embedded finance can scale responsibly. For a country where 44–50% of adults remain unbanked, this regulatory clarity is not just good policy — it is a prerequisite for closing the financial inclusion gap.